USDA Home Loan Cosigner Rules: Can Someone Co-Sign Your USDA Mortgage?
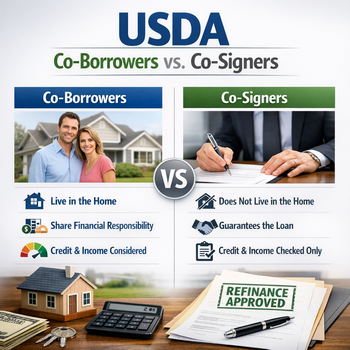 Many buyers ask the same question when their income or credit falls short: can a parent or relative sign as a USDA home loan cosigner? The short answer surprises people. The USDA guaranteed program does not allow a traditional cosigner who stays in another home. You can still add a co-borrower, but that person must live in the house with you.
This guide explains how cosigning works on a USDA loan, who counts as an eligible co-borrower, how the extra income affects your household income limit, and what other mortgage options exist when a non-occupant cosigner is your only path to approval.
Can You Have a Cosigner on a USDA Loan?
The U.S. Department of Agriculture runs two home purchase programs. The Section 502 Guaranteed program works through a private mortgage lender. The Section 502 Direct program works through your local USDA direct loan office. Each one treats cosigners differently.
USDA Handbook HB-1-3555, Chapter 9.8, bars cosigners and non-occupant co-borrowers on guaranteed loans. Every borrower on the note must personally occupy the home as a primary residence. Approved lenders repeat this rule in their own product guides, so no one will make an exception. A buyer who wants to become a homeowner with outside help needs a different plan.
The Direct program follows a different rulebook, found in 7 CFR Part 3550. It allows a cosigner in limited cases when the applicant cannot show enough repayment ability alone. Under that rule, the cosigner becomes jointly liable on the mortgage loan for the note but gets no ownership interest in the property.
| Program | Non-Occupant Cosigner | Occupying Co-Borrower | Who Approves |
|---|---|---|---|
| USDA Guaranteed (Section 502) | Not allowed | Allowed | Approved private lender, then USDA |
| USDA Direct (Section 502) | Allowed in limited cases | Allowed | Local USDA office |
| FHA loans | Allowed with limits | Allowed | FHA-approved lender |
| Conventional | Allowed with limits | Allowed | Lender and Fannie Mae or Freddie Mac |
Cosigner vs. Co-Borrower on a USDA Mortgage
People use these terms as if they mean the same thing. They do not. A cosigner signs the promissory note and becomes responsible for the loan if you stop paying. A cosigner does not appear on the title and does not live in the home.
A co-borrower signs the note, goes on the title, and shares ownership. On a guaranteed usda mortgage, the co-borrower must also move in and use the home as a primary residence. That occupancy rule is the dividing line.
Here is how the two roles compare on a guaranteed loan:
- A non-occupant cosigner cannot sign a USDA guaranteed note.
- An occupying co-borrower can sign, own, and live in the home.
- Most lenders cap a single loan at four borrowers.
- Every borrower must have a valid Social Security number and meet citizenship or lawful residency rules.
- Each co-borrower goes through the same credit and income review as the main applicant.
Who Qualifies as a Co-Borrower in the USDA Loan Program?
The USDA loan program does not restrict co-borrowers to spouses. A sibling, adult child, parent, or partner can join your loan application as long as that person moves into the home. Each co-borrower signs occupancy certifications at closing.
A parent who plans to sell their own house and move in with you fits the rules. A parent who wants to help but plans to stay in their current home does not. If that person keeps another home, underwriters will look closely at whether the move is real.
Co-Borrower Eligibility Requirements
To be eligible for a USDA guaranteed loan, each co-borrower must meet the same eligibility requirements as the primary buyer. Lenders pull a credit report for every person on the loan and review the credit history of each one. A co-borrower with recent collections, a past foreclosure, or delinquent federal debt can sink the whole file.
USDA also checks the CAIVRS federal debt database. Any applicant with delinquent non-tax federal debt, such as a defaulted federal student loan, will not qualify until the debt is resolved.
Credit Requirements to Qualify for a USDA Loan With a Co-Borrower
USDA does not set a hard minimum credit score in its handbook. Most lenders want a credit score of 640 or higher so the file can run through the Guaranteed Underwriting System (GUS) with streamlined credit documentation. Below 640, many lenders will still review the file through manual underwriting, but they ask for more paperwork.
The table below shows how lenders commonly treat credit requirements for each person on a USDA file:
| Credit Score | Typical Lender Treatment |
|---|---|
| 640 and above | Eligible for GUS streamlined credit review |
| 580 to 639 | Manual underwriting with extra documentation at many lenders |
| Below 580 | Most lenders decline |
| No score | Some lenders accept nontraditional credit such as rent and utility history |
Adding a co-borrower with strong credit does not erase weak credit from the main applicant. Underwriters look at every borrower. If one person has a 690 score and the other has a 560 score, the lower score often drives the decision.
Income Requirements and the Household Income Limit
This is where many buyers get caught off guard. The USDA guaranteed program caps total household income at 115 percent of the area median income. That cap counts income from every adult who lives in the home, whether or not that person signs the loan.
When you add a co-borrower, their pay counts toward that cap. A higher combined income helps your repayment ratios, but it can push your household over the limit. Check the current USDA income limits for your county before you decide who should join the loan.
Lenders review two separate income tests:
- Household income: all adult members of the household count toward the 115 percent of median cap.
- Repayment income: only the borrowers on the note count toward qualifying for the payment.
- Allowed deductions: USDA subtracts set amounts for dependent children, childcare costs, and elderly household members.
- Stable history: lenders want to see steady income, often a two-year history, for each borrower.
How Debt-to-Income Ratios Work With a Co-Borrower
USDA uses two ratios to judge whether you can carry the payment. The housing ratio limit is 29 percent of gross monthly income. The total debt-to-income ratio, or DTI, limit is 41 percent. GUS can approve higher ratios when the file shows strong compensating factors.
When you add a co-borrower, the lender adds their income and their debts. A co-borrower with a good salary and few debts can lower your combined debt-to-income numbers. A co-borrower with a large car payment or credit card balances can make them worse. Learn more about USDA debt-to-income limits before you apply.
Student loans often trip up co-borrowers. If the credit report shows a zero or deferred payment, USDA guidelines tell the lender to count 0.5 percent of the loan balance as a monthly debt. A $40,000 student balance adds $200 per month to the debt side of the ratio.
Mortgage Insurance and Upfront Fees on a USDA Loan
USDA guaranteed loans do not carry private mortgage insurance. Instead, they charge a guarantee fee that works the same way. For fiscal year 2027, USDA kept the upfront fee at 1 percent of the loan amount and the annual fee at 0.35 percent of the unpaid balance.
Most buyers roll the 1 percent fee into the new mortgage. The annual fee gets split into 12 parts and added to your monthly payment. Adding a co-borrower does not change these fees.
| Fee | Rate | Example on $250,000 Loan |
|---|---|---|
| Initial guarantee fee | 1.00% | $2,500 at closing or financed |
| Annual fee | 0.35% | About $875 per year, or $73 per month |
Property Rules: Your Home Must Be Located in an Eligible Rural Area
Co-borrowers do not change the property rules. The home must be located in a USDA-eligible rural area, which Rural Development maps by address. Many small towns and suburbs still qualify, so check the map before you rule yourself out.
The guaranteed program has no set loan limit. Your income and debt ratios decide how much you can borrow. The Direct program does use area loan limits that vary by county.
What If Your Cosigner Will Not Live in the Home?
If your helper plans to stay in their own house, the guaranteed USDA route closes. You still have options. Several mortgage products allow non-occupant family members to help a home buyer qualify.
FHA Loans and Non-Occupant Co-Borrowers
FHA loans allow a non-occupant co-borrower. When that person is a family member, FHA allows the standard 3.5 percent down payment on a one-unit home. FHA charges a higher upfront premium than USDA, and the annual premium often lasts for the life of the loan. Compare the two on our USDA vs. FHA comparison page.
Conventional Loans With a Non-Occupant Borrower
Fannie Mae and Freddie Mac also allow non-occupant borrowers. These loans need a higher credit score in most cases, and some programs limit the debt ratio of the person who lives in the home. A conventional loan can offer a lower interest rate for borrowers with strong credit.
USDA Direct Loan With a Cosigner
Buyers with lower incomes may fit the Direct program instead. It uses lower income caps than the guaranteed program and may offer payment assistance that drives the note rate down. The local USDA office decides whether a cosigner fits your case.
Risks of Cosigning a Mortgage
Anyone thinking about cosigning or joining as a co-borrower should know what they are signing up for. The debt shows up on their credit report and counts against their own debt ratios. That can make it harder for them to get a loan for their own needs later.
- Late payments damage the credit of every person on the note.
- A foreclosure stays on each borrower's credit report for seven years.
- The lender can pursue any signer for the full balance.
- Removing a co-borrower later usually requires a refinance.
- A co-borrower who moves out after closing may break the occupancy agreement.
Pros and Cons of USDA Loans With a Co-Borrower
Adding a co-borrower can open the door to homeownership for buyers who could not qualify alone. It can also create problems that show up years later. Weigh both sides before you purchase a home together.
| Pros | Cons |
|---|---|
| No down payment required | Co-borrower must live in the home |
| Combined income can lower DTI | Combined income may exceed the household cap |
| Lower fees than FHA | Both borrowers share liability |
| Competitive fixed rates | Property must sit in an eligible area |
How to Get a USDA Loan With a Co-Borrower
Start with a loan officer who closes USDA loans often. Bring pay stubs, W-2s, tax returns, and bank statements for every person who will sign. Share the names and income of every adult who will live in the home, even those who will not sign.
Your lender will check the property address, run GUS, and confirm the household income cap. Once the lender approves the file, it goes to USDA for final review. Strong files move through the home buying process in 30 to 45 days in most markets. Read our full guide to USDA loan eligibility to prepare.
A usda home loan with a co-borrower can work well when both people plan to share the home for the long haul. Keeping mortgage payments current protects every signer and keeps both credit files clean.
USDA Cosigner Questions and Answers
Can my parents cosign my USDA loan if they do not live with me?
No. The USDA guaranteed program does not allow non-occupant cosigners or co-borrowers. Your parents can join the loan only if they move into the home as their primary residence. If they will stay in their own home, look at FHA or conventional financing instead.
Does a co-borrower's income count toward the USDA income limit?
Yes. A co-borrower's income counts toward the household income cap of 115 percent of area median income. USDA also counts income from adults in the home who do not sign the loan.
What credit score does a USDA co-borrower need?
Most lenders want each borrower to have a 640 score or higher for streamlined GUS approval. Some lenders will manually underwrite scores between 580 and 639 with extra documentation.
Can I remove a co-borrower from a USDA loan later?
In most cases, you need to refinance into a new loan in your name alone. You must qualify on your own income and credit at that time. Some servicers allow a release of liability after a divorce or death, but this varies.
Does the USDA Direct loan allow cosigners?
Yes, in limited cases. The Direct program may accept a cosigner when the applicant lacks enough repayment ability alone. The cosigner shares liability for the debt but holds no ownership interest in the home. Your local USDA office makes that call.
Written by W.A. MacDonald, retired loan officer.
References and Regulatory Citations
- 7 CFR 3555.152(a) – Code of Federal Regulations, Rural Housing Service, Borrower Requirements
- HB-1-3555, Chapter 9, Section 2 – USDA Handbook 1-3555: Single Family Housing Guaranteed Loan Program Technical Handbook, Repayment Income
- HB-1-3555 Repayment Income Guidance – USDA Rural Development, Single Family Housing Guaranteed Loan Program, Repayment Income Notes
- USDA RD Single Family Housing FAQ – Frequently Asked Questions, Loan Origination, USDA Rural Development
- RD Form 3555-21 – Worksheet for Documenting Eligible Household and Repayment Income, USDA Rural Development
Connect With Us
Please share – it really helps